 Jean Chatzky
Do One Thing: Find your last rent receipt or mortgage statement and write down every charge on it. You can’t trim housing costs you can’t see.
For most people, housing costs are the biggest bill each month. Whether you rent or own, that payment can feel fixed. However, you often have more room to lower it than you think. This guide walks through the four main parts of what you pay for housing, along with simple ways to trim each one.
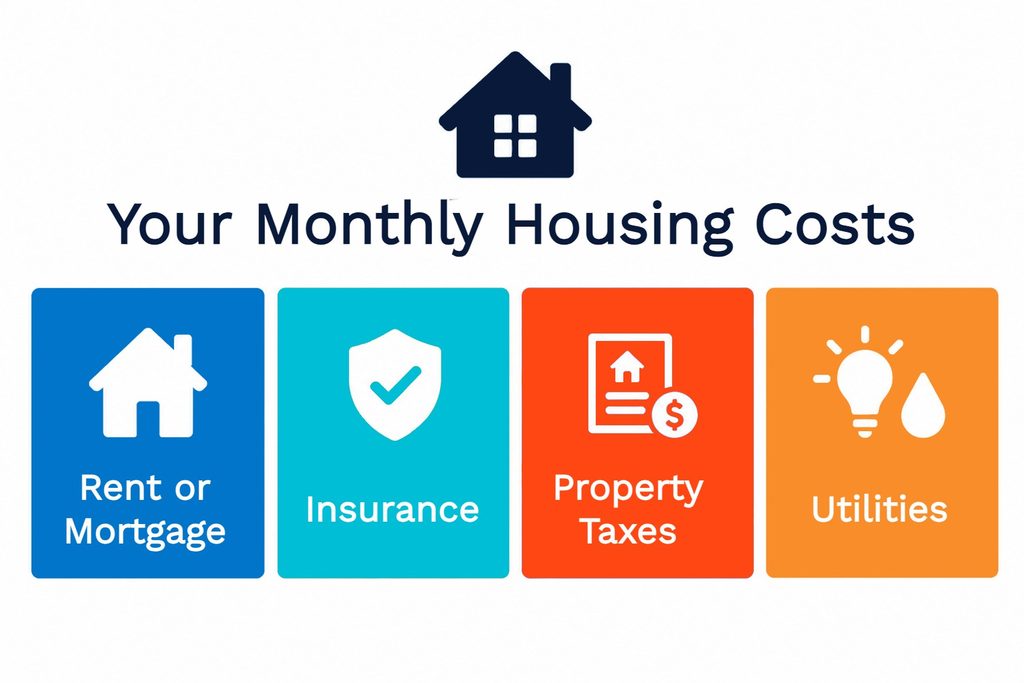
Where Your Housing Costs Come From
Your housing expenses usually include four main pieces:
- Rent or mortgage. This is your base payment, usually the largest.
- Insurance. Homeowners need homeowners insurance. Renters can buy renters insurance to protect their belongings.
- Property taxes. Homeowners pay these directly or through their mortgage. Renters pay them indirectly, since landlords build them into rent.
- Utilities and upkeep. For tips on these, see our guide to utilities, maintenance, and other everyday costs.
Lower Your Rent
Rent is often the biggest piece of your housing costs, and it’s more negotiable than many people think. Bri Conn, co-host of the Childfree Wealth Podcast, suggests a few ways to start:
- First, check whether your landlord lists your unit on rental sites. The listed price may be lower than what you pay now.
- Ask whether different lease lengths come with different rates. Many landlords lower the monthly rate for a longer lease.
- Also, ask about move-in dates. Some places change the price if your lease starts mid-month.
Tips for Current Tenants
Planning to renew? Conn suggests watching how often your landlord offers referral bonuses. More frequent or larger bonuses can signal that your landlord is struggling to fill units. As a result, you may have leverage to keep your rent the same.
For more ideas, read these other ways to cut your rent.
Cut Your Mortgage Costs
For homeowners, the mortgage is usually the largest of their housing costs. Fortunately, your rate isn’t always locked in forever. Here are a few options to review:
- Refinance when rates drop. A lower rate can shrink your payment. Still, refinancing has closing costs, so compare the savings with the fees first.
- Remove private mortgage insurance (PMI). If you put less than 20% down, you likely pay PMI. Once you build enough equity, you can ask your lender to drop it.
- Weigh an adjustable-rate mortgage (ARM) carefully. An ARM often starts with a lower rate than a fixed loan. However, the rate can rise after the starting period ends, and so can your payment. An ARM tends to fit best if you expect to sell or refinance before then, but you can’t count on either.
Our guide to lowering your mortgage payments covers discount points and other options.
Consider a Smaller Home
Moving costs money, so downsizing isn’t right for everyone. Still, a smaller space can lower several housing costs at once: rent or mortgage, taxes, insurance, and utilities.
Laura Lynch, a certified financial planner and founder of Financial Planning with Tiny-Living Values, encourages people to rethink how much space they need. She notes that houses have grown in square footage over time while families have gotten smaller. “It is our expectation,” she says, “of the home size that keeps us trapped in buying such a high-cost roof and paying for it for such a long time.”
Shop Your Insurance to Lower Housing Costs
Insurance is a part of housing costs that many people set and forget. Yet premiums can creep up each year, even if you never file a claim. Here are some things you can do to lower insurance costs:
- Shop around at least once a year and compare quotes from several insurers.
- Ask about discounts for bundling home and auto coverage or for safety features like smoke detectors.
- Raising your deductible can lower your premium, too.
- Just make sure you could cover that higher amount from savings if something goes wrong.
If you rent, renters insurance is often affordable, and it can save you from replacing everything out of pocket after a fire or theft.
Check Your Property Tax Bill
Your local government sets property taxes using your home’s assessed value. For many homeowners, taxes are a large share of housing costs, so it pays to check. Sometimes that value is too high or contains errors, such as the wrong square footage. To check for accuracy and potential savings, do a quick review every year:
- Review your assessment notice carefully when it arrives.
- If something looks off, you can usually file an appeal with your local assessor’s office.
- Additionally, ask whether you qualify for exemptions, such as a homestead exemption.
- However, rules vary by state and county. If you pay your taxes and insurance through escrow, lowering either one can also lower your monthly mortgage payment.
How Credit Affects Your Housing Costs
Your credit can play a role in whether you rent or buy. Landlords often check credit when they screen applicants. A stronger credit history can help a landlord approve you and may mean a smaller security deposit.
Boost Credit Score
For buyers, a higher credit score can help you qualify for a lower mortgage rate. Even a small rate difference adds up over the life of a loan. Renters can also build credit through rent reporting. In fact, VantageScore research found that adding on-time rent payments helped many renters reach scores high enough to qualify for a mortgage. Learn how rent reporting works.
Manage Your DTI
Lenders also look at your debt-to-income ratio, or DTI. This number shows how much of your monthly income goes to debt payments. Paying down debt can lower your DTI and improve your loan options.
See how mortgage lenders calculate DTI for the details.
Small Steps Toward Lower Housing Costs
You don’t have to tackle everything at once. It’s a process. Start with one piece, like shopping your insurance or checking your tax assessment. Then move to the next. Over time, those changes can make your housing costs easier to manage.
With reporting by Casandra Andrews
 Chris O'Shea


